Klarna Seeks U.S. Industrial Bank Charter As Partner-Bank Model Faces Review
Banking Dive reported that Klarna applied for a U.S. industrial bank charter after the company said it had extended $91.3 billion in credit to U.S. consumers; the application still needs FDIC and Utah approval.
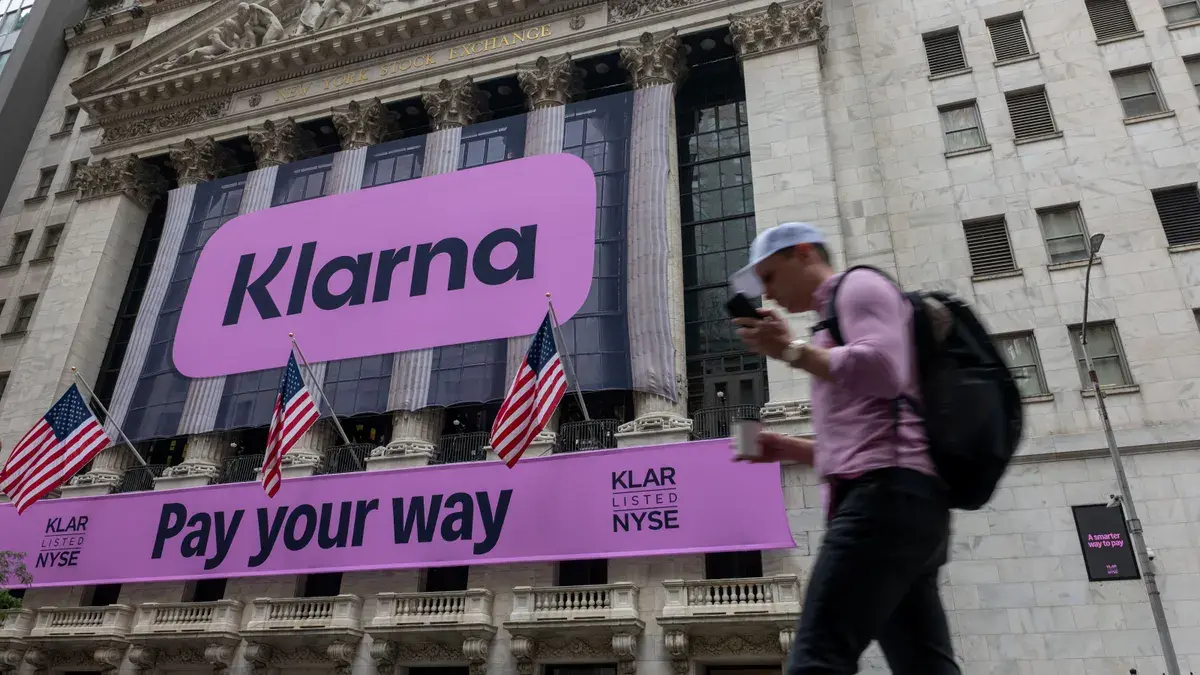
Klarna's U.S. industrial bank charter application would move part of the buy now, pay later company's American lending model inside its own regulated bank if federal and Utah authorities approve it.
Banking Dive reported that the company applied with the Federal Deposit Insurance Corp. and Utah's Department of Financial Institutions for a charter to run an industrial bank.
Industrial Bank Charter Would Bring Lending In-House
The Swedish fintech already operates as a bank in Europe under a licence it has held since 2017, while its U.S. services have relied on partner financial institutions, often WebBank.
A spokesperson declined to comment to Banking Dive on other bank partners or intermediaries.
The licence would let the company bring more financial services under its own control.
Chief executive Sebastian Siemiatkowski said an in-house banking licence was a natural next step that would give customers tools to borrow responsibly and build financial confidence, while bringing more competition and choice to consumers and merchants.
Klarna is still headquartered in Stockholm, but its U.S. push is now central to the company.
Banking Dive reported that it registered in London for its initial public stock offering last year, and a spokesperson told the outlet that the United States leads its revenue base and investor exposure.
U.S. Credit Volume Gives The Application Scale
The company release cited by Banking Dive said Klarna has extended $91.3 billion in credit to millions of U.S. consumers since 2019, with hundreds of thousands of merchants using its services.
Its website lists about 119 million active consumers worldwide and about 1 million merchants, including Sephora, H&M and Adidas, across 26 countries.
ILC Charters Face Federal Reserve Oversight Debate
The charter route is politically sensitive because industrial loan companies can be owned by commercial firms without the same Federal Reserve holding-company oversight that applies to many banks.
Some Republican and Democratic lawmakers, backed by the banking industry, argue that ILCs can avoid the definition of a bank under the Bank Holding Company Act as long as they do not offer demand deposit accounts, according to Banking Dive.
Senators John Kennedy and Andy Kim introduced a bill in January to close what they called the shadow banking loophole.
The measure remains before the Senate Banking Committee.
The Independent Community Bankers of America said in May that removing the Fed from ILC supervision leaves a safety-and-soundness gap and adds systemic risk.
Regulators have also approved several recent ILC applications.
Stellantis received approval in May to launch an ILC, Ford and GM received green lights in January, and Edward Jones followed in February.
FDIC Chair Travis Hill last year described the ILC charter as one way to increase the creation of new banks.
Approval Timing And Product Launch Dates Remain Open
If the charter is approved with FDIC insurance, the proposed bank would operate as a subsidiary headed by Gary Harding, formerly chief executive of Milestone Bank and Prime Alliance Bank, according to Banking Dive.
The public record still lacks an FDIC decision timetable, Utah approval conditions, deposit product launch dates and a measure of how much partner-bank volume would move inside the proposed industrial bank.