Taktile Raises $110 Million As Banks Test AI Agent Oversight
Taktile raised $110 million for financial-services AI agents, PYMNTS reported. Bank customers, valuation, benchmark methodology or regulator-reviewed deployment evidence remain outside the public record.
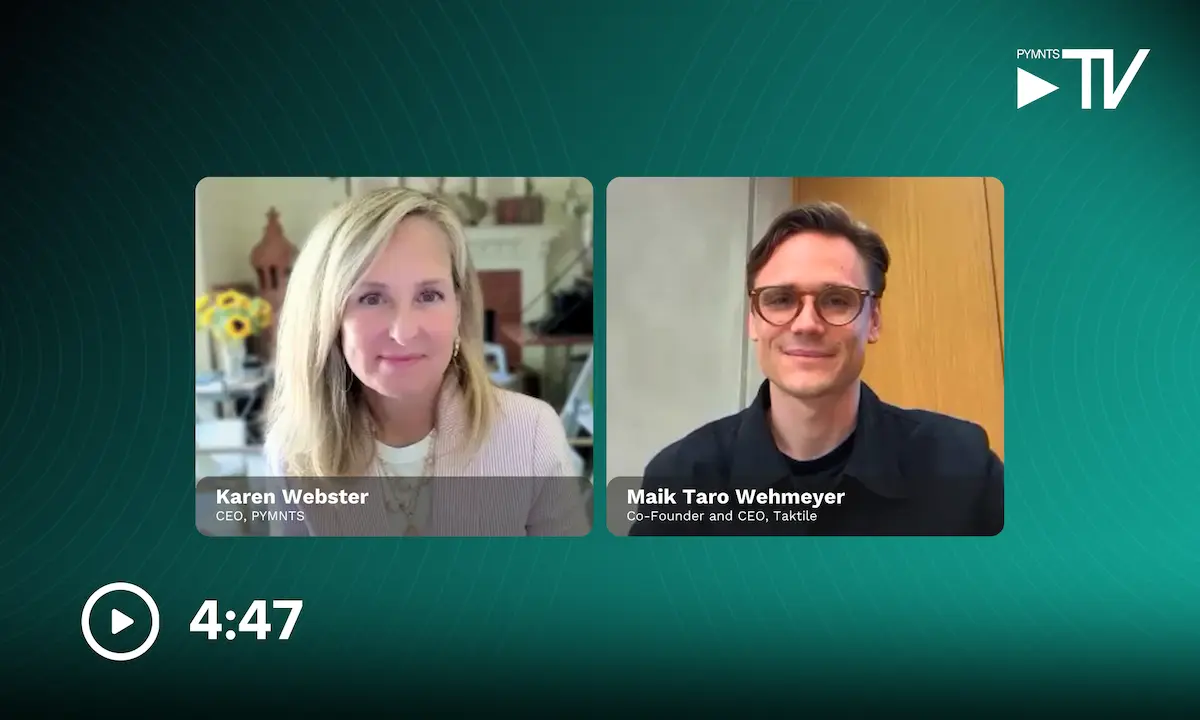
Taktile raised $110 million as regulated banks test AI agents in lending, KYB, fraud and claims workflows, PYMNTS reported.
The banking AI agent funding round, led by Goldman Sachs Alternatives, gives the decisioning platform more capital as banks test whether AI can support account opening, lending, know-your-business checks, fraud work and claims decisions.
Taktile co-founder and CEO Maik Taro Wehmeyer told PYMNTS that financial institutions are moving from experiments toward production, while many banks still hesitate to give AI access to core systems.
Taktile Raises $110 Million For Financial Decisioning AI
Goldman Sachs Alternatives led the round, according to PYMNTS.
Taktile sells its platform to regulated financial institutions that want AI agents to help complete complex operational workflows while keeping oversight in place.
Wehmeyer described 2026 as the year AI comes to financial services.
His argument was not that banks are ready to remove human control from every decision.
He said models are becoming strong enough for mission-critical financial workflows, while banks, regulators and executives still need proof that those systems can be trusted.
Taktile is trying to move AI beyond document summaries and employee assistance, according to PYMNTS.
Its examples included commercial lending, insurance claims management and business underwriting.
Those are regulated workflows where speed, explainability and accountability matter because decisions can affect credit, claims payments and customer access.
Banks Are Testing Agents For Lending, KYB, Fraud And Claims
Wehmeyer sees conversational AI becoming a primary interface for opening accounts, applying for loans and interacting with financial institutions, according to the report.
He also said thousands of banks remain cautious, even as a smaller group has moved into production.
The interview cited potential workflow changes rather than audited customer outcomes.
In Wehmeyer's examples, lenders could compress small-business loan decisions from a multi-week manual process to minutes, and insurers could shorten claims reviews by using drone imagery with AI-assisted damage assessment.
Those examples remain interview claims rather than audited customer outcomes.
The public record does not yet include named bank customers, production volumes, approval rates, default outcomes, claims accuracy, fraud-loss reductions or regulator-reviewed performance results.
Community Banks May Move Faster After Cloud Modernisation
AI readiness varies by institution rather than size, according to PYMNTS.
Some large banks remain hesitant, while some community banks and credit unions have adopted AI more aggressively after wider cloud modernisation work.
The interview used a size comparison to describe the competitive pressure.
It said a $2 billion-asset credit union could use decisioning tools that were previously more common at institutions with far larger technical teams, while a $2 trillion-asset bank can also compete on faster loan decisions.
Smaller financial institutions want the decision speed of larger rivals without building large internal data-science teams.
The report quoted Wehmeyer as saying many people confuse AI transformation with cost savings, while the larger advantage is compressing decision times.
Taktile Labs Benchmarks Are Meant To Support Trust
Taktile has created Taktile Labs to benchmark AI performance against human experts across financial use cases, according to the report.
The lab publishes ongoing data on model performance across underwriting, KYB, fraud and claims.
The company also encourages customers to run AI in shadow mode.
In that setup, institutions can compare AI recommendations with existing human workflows before giving systems operational authority.
Regulated lenders and insurers still have to explain decisions to auditors, executives and supervisors.
The remaining public-record gaps are benchmark methodology, independent validation, regulator approval, customer-level results, named production bank users, the number of decisions processed on the platform, valuation, contract terms and regulator-reviewed deployment evidence.